Business-Promo-Strip-Agribusiness1

Agri-Business Loan

Fueling the Caribbean's food security mission

Grow your agri business with special reduced interest rates for eligible Agri-SMEs

HYDROPONICS FINANCING

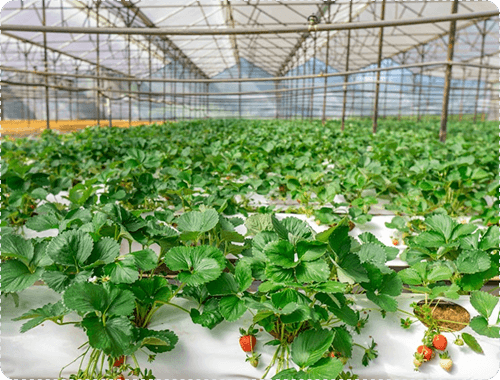
Grow smarter with hydroponic farming

An additional TT$20 million has been earmarked specifically for hydroponic farming, bringing total agribusiness allocation to TT$70 million. Promote sustainable agricultural practices and address food security through innovation

  • Equipment financing — pumps, NFT channels, greenhouses, lighting
  • Working capital for seedlings, fertilizers, and maintenance
  • Expansion financing to grow capacity and diversify crops
  • Tier 1: Up to TT$150,000 (+ credit card up to US$2,500)
  • Tier 2: Up to TT$300,000 (+ credit card up to US$3,500)
agri _HYDROPONICS_FINANCING

POULTRY FINANCING

Support T&T's poultry industry

Poultry accounts for 70% of T&T's annual protein intake. This financing package supports the productivity and sustainability of the poultry industry with up to TT$400,000 in funding

  • Equipment financing — pumps, NFT channels, greenhouses, lighting
  • Infrastructure — poultry houses, coops, ventilation and cooling systems
  • Equipment — feeders, drinkers, lighting, egg collection systems
  • Working capital for feed, veterinary bills, and utilities
  • Expansion financing — larger flocks, new markets, additional houses
agri_POULTRY_FINANCING

GENERAL AGRI-BUSINESS

Financing across the value chain

Whether you're a farmer, food processor, input provider, or transporter — this loan supports your working capital needs, equipment purchases, facility improvements, and business growth

  • Working capital and operational expenses
  • Equipment purchases and facility maintenance
  • Process improvement and premises upgrades
  • Debt consolidation and restructuring
  • Vehicle purchase for business use
agri_GENERAL_AGRI-BUSINESS

Loan tiers

Two flexible tiers designed to accommodate businesses of different sizes across the agricultural sector

agri-loan_tier_1

Tier 1 
up to TT$150,000

Unsecured financing. 
•Annual turnover up to TT$500K

Registered / registration in progress
Minimum 2 years in operation
agri-loan_tier_2

Tier 2 
up to TT$400,000

Expanded financing (higher limit). •Annual turnover TT$500K–TT$8M

Registered / registration in progress
Business credit card up to US$3,500

Key benefits

Designed to support established Agri-Businesses with flexible financing across the entire agricultural value chain

Up to TT$400,000 financing

Access up to TT$150,000 unsecured under Tier 1 or up to TT$400,000 under Tier 2 to grow your agri-business

Special reduced rate — 7% fixed

Enjoy a reduced fixed interest rate of 7% designed specifically for the agricultural sector

No financial statements required

No formal financial statements needed — just verification of a minimum of 50% of declared income

Entire value chain covered

From seedlings and farming equipment to transport, wholesale, manufacturing, and retail distribution

Registered or unregistered

Both registered and unregistered businesses can qualify — as long as you have 2+ years in operation

Hydroponics financing

Specialised financing for hydroponic farming — equipment, working capital, and expansion loans

Poultry financing

Up to TT$400,000 specifically for poultry operations — infrastructure, equipment, feed, and expansion

Business credit card option

Eligible borrowers can include a business credit card with limits up to US$3,500 depending on tier

Frequently asked questions

Have questions?

Learn more about our agri-loans

  • Would start-up businesses qualify for this facility?
    Start-up businesses will not be able to qualify for this facility. This product is geared towards established operations with more than 2 years in business, subject to advice from the technical support network/Agri-Specialist at the SME Development Unit
  • Would only farmers qualify for this type of product?
    Any business or individual can qualify within the Agri-Business value chain
  • Which businesses fall within the Agri-Business value chain?
    Any agri-type business including seedlings, transport or rental of farm equipment, wholesale/retail, farmers, manufacturing, poultry, livestock, fishing, aquaponics, hydroponics, and similar activities within the value chain
  • What type of businesses are considered Secondary Processors with established commercial/wholesale links?
    These are businesses that transform raw agricultural products into value-added goods and often have established commercial or wholesale connections. Examples include food processors, food packaging companies, juice or sauce producers, and companies producing frozen or dried foods
  • Will financial statements be required for assessment of the facility?
    Financial statements are not required. However, verification of at least 50% of declared income is required through account deposits or invoices
  • Can a customer avail of both an MSME Loan and an Agri-Business Loan?
    Existing MSME loans must be consolidated into the Agri-Business Loan request. Customers cannot hold both facilities simultaneously
  • Is there a dollar value ceiling for the product per customer?
    Tier 1: up to TT$150,000 and may include a business credit card up to US$2,500. Tier 2: up to TT$300,000 and may include a business credit card up to US$2,500. The combined loan and credit card amount cannot exceed the tier maximum
  • Does the borrower have to be a resident of Trinidad and Tobago?
    The borrower should be a CARICOM national
  • What type of business is considered an input provider?
    Input providers in the agricultural value chain are businesses or entities that supply various inputs necessary for farming activities.
    These inputs can include:
    • Seeds and seedlings
    • Fertilizers and soil amendments
    • Pesticides and herbicides
    • Agricultural machinery and equipment
    • Irrigation systems
    • Livestock feed
    • Veterinary services and animal health products
    • Agrochemicals
    • Farming tools and implement
  • What is the rate applied to this product?
    A reduced / special rate of 7% Fixed will be applied
  • Who can apply for an agri-business loan?
    CARICOM nationals operating established businesses for over two years across the agriculture value chain can apply
  • What crop and livestock cycles qualify for short-term financing?
    Loans cover short-term crops harvested within 4 to 20 weeks and livestock cycles ranging from 6 weeks to 12 months. Read more on our loan pages

Hydroponics

Get answers to the most common questions about Agri-Business Loans for Hydroponics.

  • What type of businesses are considered Producers?
    Businesses classified as producers typically include: • Drip to waste
    • Nutrient Film Technique (NFT)
    • Any other soilless methods
  • What type of businesses are considered input providers?
    Input providers assist in pre-production inputs. These inputs can include:
    • Greenhouse-grade fertilizers (NPK, Cal, Mg)
    • Suppliers of drip-tape, valves, sprinklers / misters
    • Builders of shade houses \ greenhouses
  • What can the loan be used for?
    It can be used for, but not limited to, any or all of the following:
    1. Equipment Financing to purchase hydroponic essentials including:
    • Irrigation equipment such as water pumps and installation of misting systems and reservoirs.
    • Structural equipment such as Nutrient Film Technique (NFT) channels, drip-to-waste racks, and construction of greenhouses.
    • Electrical equipment such as lighting fixtures and digital timers.
    • Mechanical equipment such as mist blowers and testers.
    2. Working Capital Loans to cover ongoing operational expenses, including seedlings, greenhouse grade fertilizers, and general system maintenance.
    3. Expansion Financing for farmers looking to grow their businesses, reach broader markets, diversify their crop offerings, or simply increase capacity.
  • How much can I borrow with a hydroponics loan?
    You can borrow up to TT$150,000 for smaller projects, or up to TT$300,000 for larger farm expansions, with optional credit card limits up to US$2,500
  • What type of businesses are considered Secondary Processors?
    Businesses classified as Secondary Processors typically involve:
    • Storing and processing products into finished goods such as meat, liquid, and powdered eggs.
    • Provision of non-basic packaging.
    • Transportation
  • What type of businesses are considered input providers?
    Input providers assist in pre-production inputs. These inputs can include:
    • Hatcheries
    • Chicks
    • Feed and medication
    • Veterinary services
    • Equipment
  • What can i use a poultry loan for?
    You can finance poultry houses, renovation and upgrades, new equipment, veterinary care, and business expansion up to TT$400,000
  • Who qualifies as a poultry input provider?
    Input providers include businesses supplying chicks, feed, medication, veterinary services, and poultry equipment

Ready to grow your agri-business?

Apply online and we'll contact you within 2 business days. Join the initiative to strengthen CARICOM's food security

Explore payment solutions